If you are looking to hit the trails, cruise the open water, or conquer the snow, having a less-than-perfect credit score shouldn’t stand between you and your next adventure. Many Canadians assume that a low credit score means an automatic rejection from lenders. Fortunately, specialized online lenders make it possible to secure powersports financing, even if your financial history has some bumps along the way.
Below, we answer the most common questions about securing powersports loans across Canada with bad credit.
Can you finance an ATV with bad credit?
Yes, you absolutely can. Traditional banks and major financial institutions often rely strictly on automated credit score cutoffs, making it difficult to secure an ATV loan if your credit is bruised. However, specialized powersports financing companies look at the bigger picture. They evaluate your current income, employment stability, and ability to make consistent payments rather than just focusing on your past credit score.
Can you get approved outside Ontario?
Yes! While many regional dealerships and lenders restrict their services to local areas, specialized online lenders operate nationwide. This means you are not limited by your geographic location within the country.
Which provinces can apply?
Online powersports financing platforms are designed to serve riders from coast to coast. Whether you reside in British Columbia, Alberta, Saskatchewan, Manitoba, Ontario, Quebec, or the Atlantic provinces, you can submit an application online and connect with lenders who understand your provincial market.
What credit score is needed?
There is no strict minimum credit score required to apply for online powersports financing. While traditional lenders usually look for prime scores (typically 660 and above), specialized bad credit lenders work with subprime scores, past defaults, or individuals with no established credit history at all. The goal is to find a manageable monthly payment plan that fits your current budget while helping you rebuild your credit rating over time.
What documents are required?
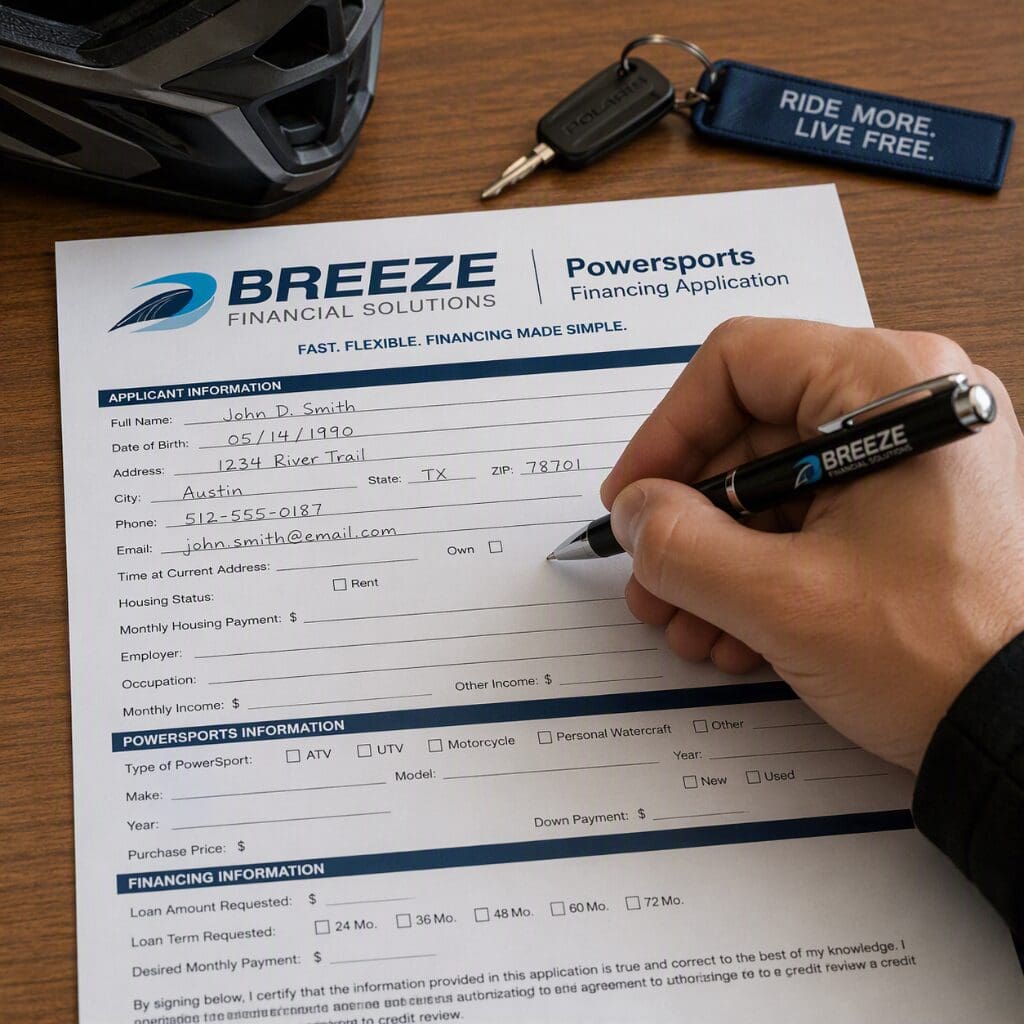
To streamline your approval process, lenders typically request a few standard documents to verify your identity and financial stability. Be prepared to provide:
- Government-issued photo ID (Driver’s license or passport)
- Proof of income (Recent pay stubs or tax documents if self-employed)
- Proof of residence (Utility bill or lease agreement)
- Bank statements (To verify active banking history and funds)
Can self-employed applicants qualify?
Yes. Being self-employed or a freelancer should not disqualify you from getting on a new machine. While traditional banks can make proving variable income difficult, specialized lenders routinely work with self-employed Canadians by reviewing alternative income verification methods, such as recent bank statements or Notice of Assessments (NOAs).
Can you get approved after bankruptcy?
Yes, getting approved for powersports financing after or even during a discharged bankruptcy is entirely possible. Many lenders specialize in post-bankruptcy financing. Consistently making timely loan payments on a powersports vehicle is actually one of the most effective ways to demonstrate financial recovery and rebuild your credit score.
Can you get approved after a consumer proposal?
Yes. If you have filed or completed a consumer proposal, you can still qualify for financing. Lenders will look at your current budget, court-approved arrangement status, and steady income to ensure that a new powersports loan is comfortable and sustainable for your financial recovery plan.
What powersports vehicles can be financed?
Bad credit financing isn’t just restricted to standard four-wheelers. You can secure loans for a wide variety of adventure vehicles, including:
- ATVs and quad bikes
- Side-by-sides (UTVs)
- Dirt bikes and motocross bikes
- Jet skis and personal watercraft (PWC)
- Snowmobiles
Why online powersports financing works across Canada
Going through traditional local dealerships often limits your options to their in-house or preferred partner lenders, which can result in rigid terms if your credit isn’t pristine. Online powersports financing platforms provide a distinct advantage by partnering with a vast, nationwide network of alternative lenders.
By applying online, your application is matched with lenders who specialize in unique financial backgrounds, self-employment, and credit rehabilitation. This streamlined approach offers higher approval rates, flexible terms, transparent communication, and fast approvals—giving you the freedom to shop for your vehicle and get back outdoors, no matter where you live in Canada.
Interested in getting support on your powersports vehicle or equipment financing application? Start your online application here.